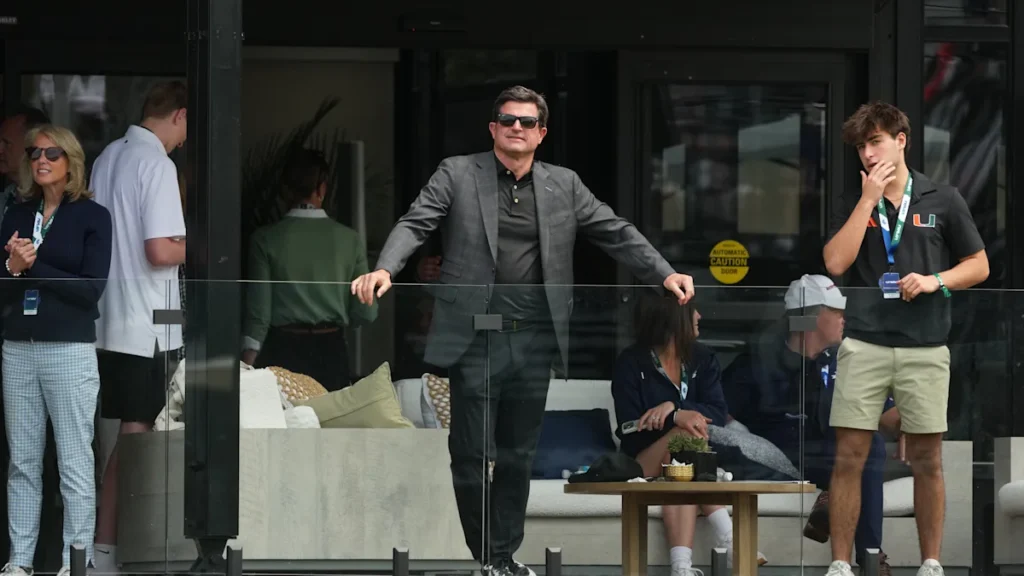

Court records filed in U.S. Bankruptcy Court in New Jersey reveal that LIV Golf allocated $15.6 million to retain seven key executives in the critical months following Saudi Arabia’s Public Investment Fund (PIF) withdrawal of financial support. The disclosures, submitted late Thursday, detail a $6.375 million payment to CEO Scott O’Neil, highlighting aggressive retention strategies employed just before the league’s Chapter 11 filing on September 8. These figures underscore the significant capital outflow during the transition period, with documents also listing 129 payments to creditors made within the 90 days preceding the bankruptcy petition.
Key Match Highlights & Tactical Analysis
The filings expose substantial compensation packages for high-profile figures, including a $26 million payment to world No. 1 Jon Rahm in the year prior to the filing. Additionally, former CEO Greg Norman, who departed in January 2025, received a $5.8 million settlement and a $3.6 million bonus on September 26, 2025. These expenditures occurred against a backdrop where the PIF had previously invested over $5 billion since the league’s June 2022 launch, funding nine-figure bonuses for top PGA and European Tour players to secure their participation.
LIV Golf is now attempting to restructure as “LIV 2.0” with a pledge of up to $300 million from BC Partners Credit, aiming to survive without its primary state-backed funder. The success of this new venture hinges on retaining its star roster, as top players like Rahm, Sergio Garcia, Louis Oosthuizen, and Adrian Meronk remain central to the league’s competitive viability. As the bankruptcy process unfolds, the focus shifts to whether these elite athletes will stay put, ensuring the league can maintain its market relevance and attract future investment.
Source: Yahoo Sports